
- Education
- Certificates & Valuations
- Jewellery Valuation for Insurance, Explained
Certificates & valuations
Jewellery Valuation for Insurance, Explained
A jewellery valuation for insurance is the document your insurer relies on if a ring is lost, stolen or damaged. A vague one can leave you under-covered, so it pays to know what a good valuation looks like.
 Reviewed by Raj Sood, Graduate Gemologist (GIA), AJP (GIA)Master jeweller and Graduate Gemologist (GIA) · reviewed 4 November 2026
Quick answer
A jewellery valuation for insurance is a written report from a qualified valuer that describes your piece in detail and states what it would cost to replace with an equivalent item at retail in Australia today. Insurers use it to set your sum insured and to replace the item accurately if you make a claim.
What is a jewellery valuation for insurance?
An insurance valuation is a written, signed document that does two jobs. First, it describes the piece precisely enough that someone who has never seen it could source or make an equivalent. Second, it gives a replacement value: what it would cost, at the time of the valuation, to buy that equivalent item new from a retail jeweller in Australia.
It is not the same as a diamond grading report. A report from a laboratory such as GIA or IGI describes the diamond's characteristics and gives no price at all; a valuation puts a dollar figure on the whole piece, including the setting and any side stones. Our guide to the difference between a valuation and a certificate goes through this side by side.
Insurers ask for a valuation for items above a certain value so they can set your premium, confirm what they are covering and, if you claim, replace the piece rather than guess. Each insurer sets its own threshold for when a valuation is required, so check your policy wording.
What should a jewellery valuation for insurance include?
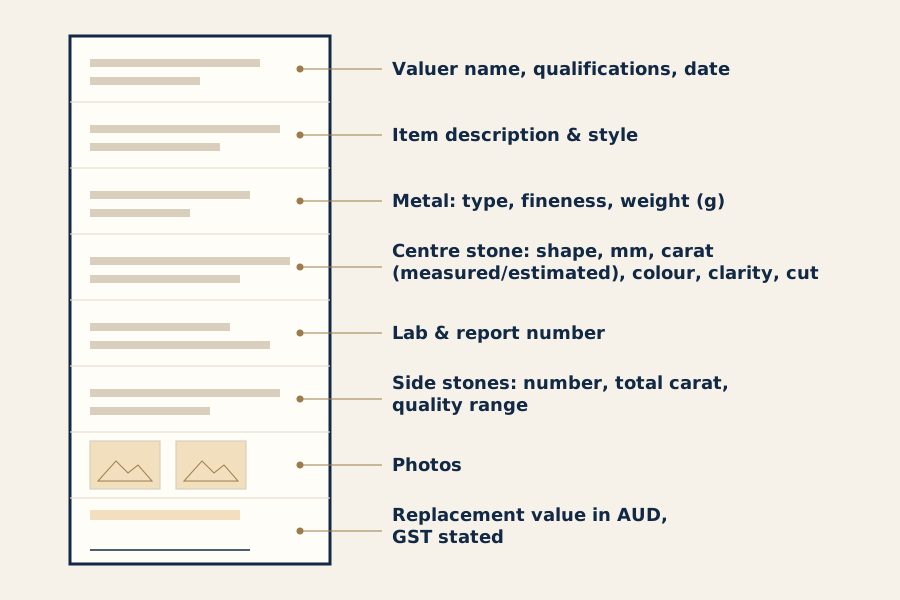
A good valuation reads like a specification. If your piece were lost tomorrow, the document alone should let a jeweller recreate it. Look for each of these:
| Section | What it should state | Why it matters |
|---|---|---|
| Item description | Type of piece, style, setting (claw, bezel, halo), finish and any engraving | Lets the insurer match the design, not just the stones |
| Metal | Metal type and fineness (for example 18ct white gold, platinum 950) and weight in grams | Metal is a real part of the replacement cost |
| Centre stone | Shape, measurements in mm, carat weight (stated as measured or estimated), colour, clarity and cut | The single biggest driver of value |
| Grading report | Laboratory, report number and whether the stone was checked against it | Ties the valuation to an independent description |
| Side stones | Number, shape, total carat weight and an estimated quality range | Pavé and halos add up quickly |
| Photos | Clear images of the piece from several angles | Helps confirm identity and design at claim time |
| Value | Replacement value in Australian dollars, stating whether GST is included | Sets your sum insured |
| Valuer details | Name, qualifications, signature and date | Shows who stands behind the figure |
If a valuation only says something like "diamond ring, approx. 1 carat, white gold" with a number underneath, it gives your insurer very little to work with. How the piece was made matters too: a ring made by hand at the bench takes more labour to remake than a cast one, so a good valuation notes it. Our guide to cast versus hand-fabricated jewellery explains the difference.
Why is an insurance valuation higher than what I could sell it for?
Because it answers a different question. An insurance valuation states retail replacement value: what you would pay a jeweller to buy or make the same piece new. What you could sell it for, its resale value, is usually much lower, because a buyer of second-hand jewellery is paying a trade or second-hand price, not a retail one.
| Type of value | The question it answers | Typical use |
|---|---|---|
| Retail replacement | What would it cost to replace new at retail? | Insurance |
| Fair market value | What would a willing buyer pay a willing seller? | Estates, family law, some tax matters |
| Resale or second-hand | What would a dealer pay for it today? | Selling a piece |
None of these is the "real" value; each suits a different purpose. That is why replacement value vs resale value is a common source of confusion when people first read a valuation. For estates or a property settlement you need a different kind of document entirely: see valuations for estates and family law.
Related guideJewellery and Diamond ValuationHow do insurers use a valuation when you claim?
Most Australian home-contents and jewellery policies give the insurer a choice: replace the item, repair it, or pay you an amount. Many insurers prefer to replace through their own suppliers, which is why the description matters so much. A detailed valuation makes it far more likely that what you get back matches what you lost.
- Agreed value: the policy covers a specific amount you and the insurer agree, often based on your valuation.
- Replacement value: the insurer pays what it costs them to replace the item at the time of the claim, up to your limit. A market-value policy may pay less, allowing for age and wear.
- Item limits: many contents policies cap any single piece of jewellery unless you list it separately.
Policy types and wording vary between insurers, so read the product disclosure statement or ask your insurer how they settle jewellery claims. Our overview of how jewellery insurance works in Australia covers the main policy types and the questions worth asking before you sign.
Not sure which one is right?
Send us the stones you are looking at and our gemologist will tell you which to choose and why.
Does my diamond need a grading report for a valuation?
No, but it helps a great deal. A valuer can grade an unreported stone in its setting, but grading a mounted diamond is less precise: the claws hide part of the stone and the carat weight has to be estimated from measurements. When a stone has a report from a recognised laboratory, the valuer can check the stone against it and quote the report number. Our guide to certified and uncertified diamonds explains why this makes such a difference.
Many diamonds carry a tiny laser inscription of their report number on the girdle, which lets a valuer match stone to report under magnification. Our guide to what a laser inscription does and does not prove explains its limits, and what a grading report leaves out covers the details a valuer still has to judge by eye.
The laboratory also matters, because grading standards are not identical everywhere. A valuer will usually value a stone on how it actually grades, not only on what the paperwork says. See GIA vs IGI vs HRD, the wider comparison of diamond grading labs, and our notes on GSI and EGL reports. If your stone has an IGI or HRD report, our walk-throughs of the IGI natural diamond report and the HRD diamond report show where each detail sits.
How are lab-grown diamonds valued for insurance?
The same way: the valuer describes the piece and states what it would cost to replace with an equivalent laboratory-grown diamond at retail today. The valuation must clearly identify the stone as lab-grown. Lab-grown diamond prices have changed quickly in recent years, which is a good reason to revalue lab-grown pieces more often so the sum insured stays realistic.
If you are not sure whether a stone is natural or lab-grown, a valuer can send it for testing; a grading report from a laboratory will state whether it is natural or laboratory-grown. Diamond origin reports go a step further for natural diamonds by tracing where a stone came from, which some owners like to keep with their valuation.
How often should you revalue jewellery?
Prices for gold, platinum and diamonds move, so a valuation slowly drifts out of date. Many valuers and insurers suggest revaluing every two to three years, and sooner when metal prices have moved sharply, after you have the piece remodelled or resized, or when you add stones. Check whether your insurer specifies an interval.
An out-of-date valuation can leave you under-insured if prices have risen, or paying a higher premium than you need if they have fallen. Our guide to how often to revalue jewellery goes through the triggers in more detail.
How do you choose a jewellery valuer in Australia?
In Australia, anyone can call themselves a valuer, so look at qualifications and process rather than the title alone. Things worth asking:
- Gemmological training: a recognised gemmology qualification, such as a diploma from the Gemmological Association of Australia or a Graduate Gemologist (GIA) diploma.
- Valuer registration: whether they are registered with a professional valuers' body, such as the National Council of Jewellery Valuers, which sets standards for valuation practice.
- Equipment: a proper loupe or microscope, accurate scales, gauges and a way to test metal and identify stones.
- Fees: how the fee is calculated. A flat fee or a fee per item is generally considered better practice than a percentage of the value, which can reward a higher figure.
- Independence: whether they also sell jewellery, and if so how they keep valuations objective.
A valuation done at the time of purchase is common and perfectly normal, as long as the description is thorough and the value reflects real retail replacement cost. Understanding the stone itself helps you read any valuation: start with the certificates and reports hub and keep the jewellery glossary open for unfamiliar terms.
GemTrove valuations and diamonds
How to get a jewellery valuation for insurance: step by step
- Gather your paperwork. Bring the receipt, any grading report and any earlier valuation; they speed things up and make the result more precise.
- Clean and check the piece. A clean ring is easier to grade, and a jeweller can flag loose claws or worn settings at the same time.
- Ask how the stone will be assessed. Will it be checked against its report, or graded in the setting with estimated weight?
- Read the draft. Make sure the metal, measurements, stone details and report number are all there and correct.
- Send it to your insurer. Confirm the item is listed and the sum insured matches the valuation, then diarise the next revaluation.
Free consultation
Talk to a gemologist
Compare stones in person or online with Raj Sood, Graduate Gemologist (GIA), AJP (GIA).
Book a consultationFAQ
Common questions
How much does a jewellery valuation cost in Australia?
Fees vary by valuer and by how many items and stones are involved. Ask for the fee up front, and prefer a flat or per-item fee over one calculated as a percentage of the value.
Is a diamond certificate the same as a valuation?
No. A grading report describes the diamond's characteristics and gives no value. A valuation describes the whole piece and states a replacement value for insurance.
Why is my insurance valuation so much higher than the price I was offered for my ring?
An insurance valuation states retail replacement cost. A dealer buying second-hand jewellery pays a trade price, which is usually much lower.
Will over-valuing my ring get me more if I claim?
Usually not. Many policies let the insurer replace the item or pay what replacement costs them, so a higher figure mainly increases your premium.
Can a valuation be done while the diamond is still set?
Yes. The valuer grades it in the setting and estimates the carat weight from measurements, which is less precise than grading a loose stone or checking it against a report.
Do lab-grown diamonds need an insurance valuation?
If the piece is valuable enough to insure separately, yes. The valuation should clearly state the stone is laboratory-grown and reflect current lab-grown replacement prices.
Ask a gemologist
Not sure which diamond to choose?
Raj Sood is a Graduate Gemologist (GIA) and master jeweller. Bring the stones you are considering, or send the reports, and he will tell you honestly which one is better and why.
Keep learning
Related guides
 Certificates & ValuationsJewellery and Diamond Valuation
 Buying Knowledge & Custom ProcessHow Jewellery Insurance Works in Australia
 Certificates & ValuationsHow Often to Revalue JewelleryCertificates & ValuationsJewellery Valuations for Estates and Family LawCertificates & ValuationsDiamond Certificates & Jewellery Reports
 Wedding Bands & EternityA Jewellery Valuation and a Diamond Grading Report Are Not the Same ThingCertificates & ValuationsCertified vs Uncertified DiamondsCertificates & ValuationsDiamond Grading Labs Compared
Explore more
More guides on this topic
Education